The LightBox Signal: Weekly Analysis of the Top CRE Headlines
Our take on the news that matters in commercial real estate and property data intelligence.
TOP STORY: Chicago Office Sale Signals Potential Pivot for the Windy City
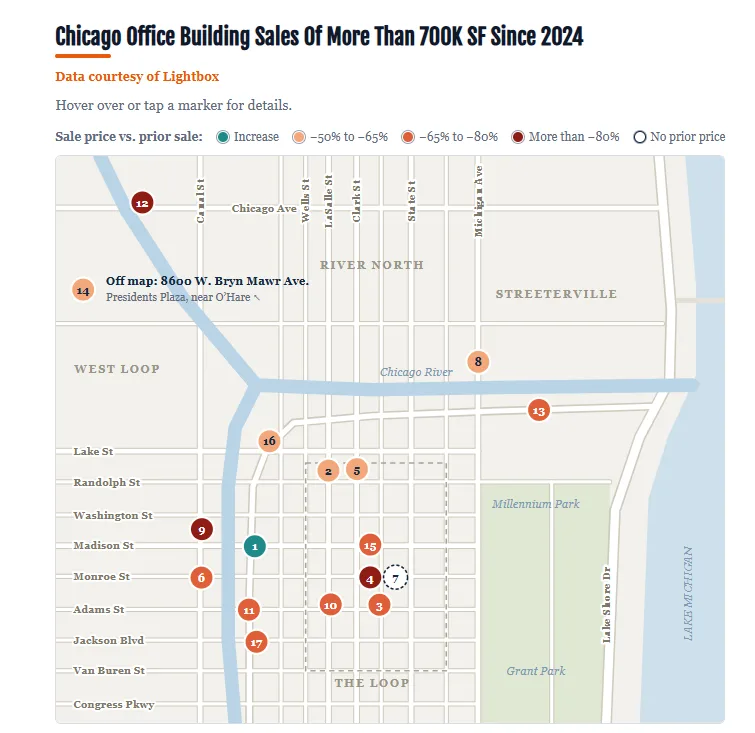
Chicago's office market may be finding its footing after years of steep valuation declines. In a Bisnow article, Mapped: Major Chicago Office Sales Since 2024, LightBox transaction data highlights the $550M sale of One North Wacker, far above recent comparable sales. Based on the data highlighted in the article, the deal is the first appreciation in a Chicago office sale exceeding 700,000 square feet since the beginning of 2024. By contrast, other large office properties with prior sale records traded at an average 71.4% discount. The significance is that this deal could establish a new pricing benchmark for trophy office assets. As LightBox Head of Data Strategy Manus Clancy told Bisnow: “One North, just by the nature of its sale, has made people question, ‘Wow, I thought I had left Chicago for dead, and now look at this one going for $400 per SF’.”
LightBox Take: Sometimes a map tells a market story better than numbers alone. Bisnow's visualization, powered by LightBox transaction data, offers a valuable glimpse into Chicago's past and present deals, illuminating where the tide may be turning. One North Wacker's premium sale is an encouraging signal, but the contrast with heavily discounted properties underscores a deeply fragmented recovery. For investors, transaction-level intelligence reveals emerging opportunities, establishes meaningful pricing benchmarks, and helps distinguish isolated outliers from broader market momentum.
Market Data Metrics: Strong Growth, Stubborn Inflation, and Rates on Hold
Last week's economic data painted a picture of a resilient economy facing mounting inflation pressures. Q3 GDP accelerated to 3.4% annualized, up from 2.2% in Q2, while October consumer confidence jumped 7.5 points to 91.7. Yet September consumer spending slowed to 0.5%, real disposable income declined, and headline PCE inflation climbed to 3.6%, with core PCE reaching 3.1%. The Fed held rates steady at 3.75%–4.00%, with two policymakers favoring a quarter-point hike.
LightBox Take: Last week's data delivered a familiar mix of encouragement and caution. Strong economic growth is good news for CRE transactions, but rising inflation and a market that’s pricing in more rate hikes paint a hazy forecast. Higher financing costs complicate refinancing, pressure valuations and make deal underwriting more challenging. This week's midterm elections introduce another layer of uncertainty around fiscal policy, government spending and Treasury yields in a market looking for more clarity as 2027 planning season gets underway.
Multifamily Investors Seeking Strongest ROI Despite Rising Rates
Despite elevated borrowing costs and economic uncertainty, multifamily investors continue writing big checks nationwide. Recent deals covered in last week’s CRE Weekly Digest include: a $130M deal for 440 apartments in Utah, a $108M transaction in Chesterfield, Virginia, a $136M closing in Austin, and a $93M deal in Charlotte. In California, a Fremont apartment complex sold for $109M, while a Northern Virginia portfolio fetched more than $230M. Utah's transaction reportedly attracted nearly 30 offers, underscoring strong investor competition for desirable assets despite persistent market headwinds.
LightBox Take: The Q3 LightBox Transaction Tracker report shows that in terms of the sheer number of deals, multifamily continues to lead CRE investment activity, accounting for 24% of all deals. What's particularly encouraging is the return of sizable deals in markets like Austin and Charlotte, where recent apartment construction has challenged fundamentals. The takeaway isn't that multifamily has recovered, but that investors are willing to look past near-term headwinds when location, pricing and long-term demand support the investment thesis.
Mega Office Construction Loan Signals Confidence in Midtown Manhattan
One of Manhattan's most ambitious office developments has secured $3.3 billion in construction financing. Vornado Realty Trust, Rudin and an affiliate of Citadel founder Ken Griffin closed the financing and joint venture on October 21 for 350 Park Avenue, a planned 66-story, 1,400-foot skyscraper encompassing more than 1.9 million square feet. The $6.2 billion project is anchored by Citadel's 15-year lease for 1.05 million square feet, leaving approximately 850,000 square feet available for other tenants. Construction is underway on the Foster + Partners-designed tower. The financing syndicate includes seven major banks: JPMorgan Chase, Wells Fargo, Bank of America, BMO, ING, PNC and Standard Chartered. Griffin's affiliate holds 60% of the development partnership, with Vornado owning 36% and Rudin 4%.
LightBox Take: The scale of this financing is remarkable in an environment where high borrowing costs have constrained new development. It also reinforces the growing divide between office's haves and have-nots. Citadel is betting that Manhattan's most desirable buildings can command premium rents and attract workers back to the office, a strategy supported by the success of nearby One Vanderbilt and JPMorgan Chase's new headquarters.
Q3’s Billion-Dollar Portfolio Deals Signal Institutional Capital Is Back in Play
Institutional investors made substantial portfolio acquisitions in Q3 2026, led by BlackRock's $1.6 billion purchase of 11 Southern California apartment communities. EQT Real Estate followed with a $1.2 billion industrial acquisition, while Stonemont and PCCP acquired 38 industrial buildings for $1 billion. Industrial accounted for five of the quarter's 10 largest portfolio deals. Senior housing also attracted major investment, with American Healthcare REIT completing acquisitions totaling $1.27 billion. Student housing joined the list with a $435 million Scion-Ares transaction.
LightBox Take: These billion-dollar commitments demonstrate that institutional capital remains available despite elevated borrowing costs and economic uncertainty. Investors are prioritizing scale, durable income and long-term demand drivers, particularly in industrial, multifamily and senior housing. The breadth of acquisitions also underscores growing confidence in alternative property types supported by demographic trends. The steady stream of big portfolios offers the latest evidence that well-capitalized buyers are finding compelling opportunities where valuations, operating fundamentals and strategic objectives align.
The Week Ahead
MONDAY | Construction spending |
TUESDAY | Job openings and labor turnover survey |
WEDNESDAY | ADP National Employment Report |
THURSDAY | Preliminary productivity |
FRIDAY | Employment report |